Parksville & Qualicum Beach

— Vancouver Island, BC

Access to Capital
Others Can't Reach.

I specialize in the complex, the creative, and the time-sensitive. Private lending, construction financing, and commercial deals that require more than a standard application and a lender list. Based in Parksville, serving clients across Vancouver Island and BC.

25 YEARS EXPERIENCE

Specializes in:

Private Lending · Construction · Commercial

Parksville · Qualicum · Vancouver Island

Private Capital Access
Construction Financing
Commercial Lending
Time-Sensitive Files
Complex Deals Welcome

What Makes the Difference

When conventional lending hits a wall,

I have options that most brokers simply don't.

My 25 years have been spent entirely in the private, construction, and commercial lending space — not dabbling in it, living in it. I have built relationships with private capital sources that move quickly, structure creatively, and say yes to deals that institutional lenders decline. If your file is complex, time-sensitive, or requires a lender who actually understands development and construction, you are in the right place.
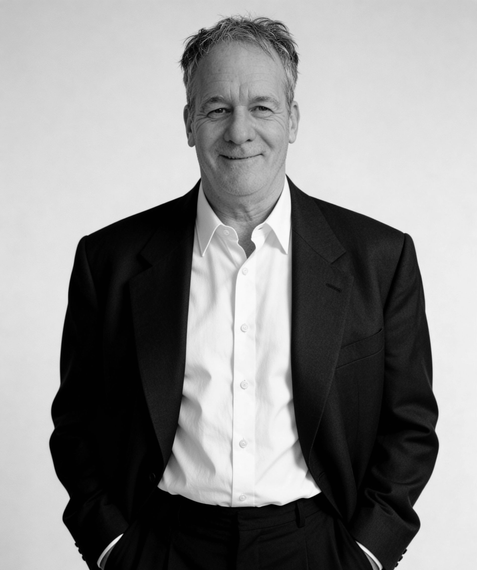
KEVIN BLUE

Mortgage Broker — 25 Years in Private, Construction & Commercial

My entire career has been spent in the lending spaces that most brokers avoid — private capital, construction financing, and commercial deals. I chose this niche intentionally because it is where complexity lives, where creativity matters, and where the right broker makes a genuine difference. Over 25 years I have built a network of private capital relationships and a depth of experience with development and construction files that cannot be replicated quickly. Based in Parksville, I work with clients across Vancouver Island and BC on files that need more than a standard application and a standard lender list.

Private Lending Construction Finance Commercial 25 Years Experience
EMAIL KEVIN

How I Work

Direct, personal, and built around your timeline.

01

Tell me the deal

The mortgage process is personal. Before we look at rates or lenders, I want to understand where you are, what you are working toward, and what is making this feel hard.

02

Access the right capital

Once I understand your situation, I will assess your financial picture, compare options across my network of lenders, and present a mortgage solution built specifically for you — not a template.

03

I stay with you

Signing is not the end. I do annual mortgage reviews for every client. When rates shift, when your life changes — I am already thinking about it too. I am your mortgage professional for life.

Services

Specialized lending for every situation.

Kevin's core expertise is private lending, construction financing, and commercial deals. He also helps Parksville and Qualicum Beach homebuyers with residential purchases — and works closely with Jody Blue for full-service coverage across the team.

01

Construction Financing

Draw mortgages, land and construction loans, spec and development financing. Complex builds handled with precision and lender relationships that understand the process.

02

Private Lending

Access to private capital sources for time-sensitive files, bridge financing, and situations where institutional lenders say no. Fast, flexible, and structured for your timeline.

03

Commercial Lending

Commercial mortgage financing for investment properties, mixed-use buildings, and business real estate across BC. Creative structures for complex commercial files.

04

Residential Purchases

Home purchase financing for buyers in Parksville, Qualicum Beach, and communities across Vancouver Island. Access to multiple lenders for the right fit.

Common Questions

Straightforward answers about private and specialized lending.

  • What is private lending and when does it make sense?

    Private lending uses capital from private investors rather than banks or institutional lenders. It moves faster, has more flexible criteria, and can structure deals that conventional lenders won't touch. It typically carries higher rates and shorter terms, making it best suited for bridge situations, time-sensitive acquisitions, construction draws, and complex files that need a creative solution before transitioning to institutional financing.

  • Can you help with construction financing in Parksville and on Vancouver Island?

    Yes. Construction and development financing is my core specialty. I work with progress draw mortgages, land and construction loans, and spec build financing for projects across Vancouver Island. If you are planning a build or development project, reach out early — the financing structure matters from the very beginning.

  • My bank declined my commercial deal. Can you find another path?

    Often yes. Commercial files that banks decline may be perfectly financeable through alternative institutional lenders or private capital sources. The answer depends on the deal — the property, the income, the structure, and the timeline. Tell me the details and I will give you an honest assessment of what is available.

  • My bank declined my commercial deal. Can you find another path?

    Often yes. Commercial files that banks decline may be perfectly financeable through alternative institutional lenders or private capital sources. The answer depends on the deal — the property, the income, the structure, and the timeline. Tell me the details and I will give you an honest assessment of what is available.

  • Do you work with residential buyers in Parksville and Qualicum Beach?

    Yes. While my specialty is private, construction, and commercial lending, I help residential buyers in Parksville, Qualicum Beach, and across Vancouver Island.

  • How quickly can a private lending deal close?

    Significantly faster than institutional lending. Private lenders do not have the same timelines as banks. In genuine time-sensitive situations we can often move from application to funding in days rather than weeks. Reach out and I will tell you what is realistic for your specific deal.

Still have a question?

CONTACT

Articles To Keep You Informed
By Kevin Blue • November 4, 2026
Why a Mortgage Pre-Approval Protects Both Your Head and Your Heart There’s no denying it—buying a home is an emotional journey. In a competitive market, it can feel like you need to stretch beyond your comfort zone or bid above asking just to have a chance. That pressure can make it hard to separate what you want from what you can realistically afford. One of the biggest pitfalls buyers face is falling in love with a home that’s outside their price range. Once that happens, every other property seems like a compromise—even the ones that might have been a perfect fit otherwise. The best way to avoid this heartache? Get pre-approved before you start shopping. What a Pre-Approval Does for You A mortgage pre-approval gives you more than just a number—it provides clarity, confidence, and protection: Know your buying power : Shop within your true price range and avoid disappointment. Spot potential roadblocks : Uncover issues like credit bureau errors before you make an offer. Get organized : Learn exactly what documentation you’ll need so there are no surprises. Lock in a rate : Many lenders hold your rate for 30–120 days, giving you peace of mind if rates rise. Save yourself heartache : Protect yourself from falling for a home you can’t afford. Head vs. Heart Buying a home is about balance. Your head tells you what’s financially sound, your heart tells you what feels right—and both matter. A pre-approval helps bring those two sides together, so you can make confident choices without emotional stress clouding your judgment. The Bottom Line Looking at properties for fun is one thing—but if you’re serious about buying, a pre-approval is the smartest first step you can take. It sets realistic expectations, saves time, and protects your emotions along the way. If you’d like to explore your options and get pre-approved, I’d be happy to walk through the process with you. Let’s make sure you’re ready to shop with confidence.
By Kevin Blue • October 28, 2026
This morning, the Bank of Canada raised its key interest rate by 0.25%, bringing it to 2.5%. Whether you own a home in Parksville or Qualicum Beach, have a renewal on the horizon, or you're in the middle of a build or commercial deal, this decision is worth understanding. Here's what changed, why it happened, and what I'd be thinking about if I were in your shoes.  Why the Bank of Canada Raised Rates The short answer is inflation. Prices have been rising faster than the Bank's 2% target, and it wants to get ahead of the problem before it spreads. Here's what's behind the decision: High energy prices. The ongoing conflict in the Middle East has kept oil prices elevated for months. Inflation has been running around 3% since April and is expected to reach about 3.5% by the end of the year. Rising business costs. Higher fuel and imported material costs are making it more expensive to produce and ship goods. The Bank expects more of those costs to be passed on to consumers over the next year. A stronger economy than expected. Canada's economy grew faster than forecast through the middle of the year, supported by solid consumer spending and a rebound in business investment. By raising rates now, the Bank is trying to stop high energy costs from pushing up the price of everything else. What This Means for Homeowners Variable-rate mortgages and HELOCs Lenders typically adjust their prime rate to match the Bank of Canada's moves, and variable mortgages and home equity lines of credit are tied to prime. Expect your rate to go up by about 0.25%. Depending on your mortgage, that means either a higher payment or more of your payment going to interest. Fixed-rate mortgages Your rate and payment won't change until your term ends. Fixed rates for new mortgages follow the bond market, and bond yields have already been rising, so fixed rates may stay elevated or move higher. Renewals If your renewal is within the next few months, start the conversation now. Many lenders let you secure a rate up to 120 days in advance, which can protect you if rates keep climbing. And please don't just sign your bank's renewal letter. It's rarely their best offer. Buyers Higher rates can reduce how much you qualify for. A pre-approval lets you hold a rate while you shop, so you know your real budget before making an offer. My mortgage calculators are a good place to start running numbers. What This Means for Builds, Commercial and Private Deals This is where rate changes can have the biggest ripple effect, and where planning ahead pays off most. Construction projects Many construction and draw mortgages are tied to prime during the build, so your interest costs may rise as funds are advanced. If you're mid-build, it's worth reviewing your budget for carrying costs. If you're planning a project, factor today's rates into your numbers from day one. Learn more about my construction financing services. Commercial borrowers Variable commercial loans will feel this increase directly. If you're refinancing or acquiring a property, higher rates can affect how lenders view your debt coverage, so the structure of the deal matters more than ever. See my commercial lending page for the types of files I work on. Private lending Private loans are usually short-term bridges to institutional financing. When rates are rising, your exit strategy deserves extra attention. Make sure the takeout financing still works at today's rates, not just the rates you assumed when the deal started. Read more about private lending . What to Expect Next The Bank of Canada said further increases are possible, but it plans to move carefully given uncertainty around energy prices and Canada-US trade. Its forecast has inflation averaging about 3% through 2027 before returning to the 2% target by mid-2028. The next rate announcement is scheduled for December 9, 2026 . Frequently Asked Questions What is the Bank of Canada's rate now? As of October 28, 2026, the Bank of Canada's policy rate is 2.5%, up from 2.25%. Will my mortgage payment go up? If you have a variable-rate mortgage, a HELOC or a prime-based construction loan, it likely will. Fixed-rate mortgages won't change until the term ends. Should I lock in a fixed rate? It depends on your terms, any penalties for switching, and your plans for the property. This is exactly what my annual mortgage reviews are for, and the right answer looks different for everyone. When is the next rate announcement? December 9, 2026. Let's Talk About Your Situation Rate changes are a good reminder to check that your financing still fits your plans. Whether you're a homeowner in Parksville or Qualicum Beach, mid-way through a build, or working on a commercial or private deal anywhere on Vancouver Island, I'd be happy to review where you stand. Reach out anytime, or apply online to get started. No obligation, no pressure. This article is for general information only and is not financial advice. Rates and lender policies change often. Please speak with a licensed mortgage professional about your specific situation.
By Kevin Blue • October 21, 2026
Don’t Forget About Closing Costs When planning to buy a home, most people focus on saving for the down payment. But the truth is, that’s only part of the equation. To actually finalize the purchase, you’ll also need to budget for closing costs —the out-of-pocket expenses that come up before you get the keys. Closing costs can add up quickly, which is why they should be part of your pre-approval conversation right from the start. Lenders will even require proof that you’ve got enough funds set aside. For example, if you’re getting an insured (high-ratio) mortgage, you’ll need at least 1.5% of the purchase price available in addition to your down payment. That means a 10% down payment actually requires 11.5% of the purchase price in cash to make everything work. Let’s break down some of the most common expenses you should prepare for: 1. Home Inspection & Appraisal Inspection : Paid by you, this gives peace of mind that the property is in good shape and doesn’t have hidden problems. Appraisal : Required by the lender to confirm value. Sometimes this is covered by mortgage insurance, sometimes by you. 2. Legal Fees A lawyer or notary is required to handle the title transfer and make sure the mortgage is properly registered. Legal fees are often one of the larger closing costs—unless you’re also responsible for property transfer tax. 3. Taxes Many provinces charge a property or land transfer tax based on the home’s purchase price. These fees can range from hundreds to thousands of dollars, so you’ll want to factor them in early. 4. Insurance Property insurance is mandatory—lenders won’t release funds without proof that the home is insured on closing day. Optional coverage like mortgage life, disability, or critical illness insurance may also be worth considering depending on your financial plan. 5. Moving Costs Whether you’re renting a truck, hiring movers, or bribing friends with pizza and gas money, moving comes with expenses. Cross-country moves especially can be surprisingly pricey. 6. Utilities & Deposits Setting up new services (electricity, water, internet) can involve connection fees or deposits, particularly if you don’t already have a payment history with the utility provider. Plan Ahead, Stress Less This list covers the big-ticket items, but every purchase is unique. That’s why it pays to have an accurate estimate of your personal closing costs before you make an offer. If you’d like help planning ahead—or want a breakdown tailored to your situation—let’s connect. I’d be happy to walk you through the numbers and make sure you’re fully prepared.
By Kevin Blue • October 14, 2026
Alternative Lending in Canada: What It Is and When It Makes Sense Not everyone fits into the traditional lending box—and that’s where alternative mortgage lenders come in. Alternative lending refers to any mortgage solution that falls outside of the typical big bank offerings. These lenders are flexible, creative, and focused on helping Canadians who may not qualify for traditional financing still access the real estate market. Let’s explore when alternative lending might be the right fit for you. 1. You Have Damaged Credit Bad credit doesn’t have to mean your homeownership dreams are over. Many alternative lenders take a big-picture approach . While credit scores matter, they’ll also look at: Stable employment Consistent income Size of your down payment or existing equity If your credit has taken a hit but you can demonstrate strong income and savings—or have a solid explanation for past credit issues— an alternative lender may approve your mortgage when a bank won’t. Pro tip: Use an alternative mortgage as a short-term solution while you rebuild your credit, then refinance into a traditional mortgage with better terms down the line. 2. You're Self-Employed Being your own boss has its perks—but mortgage approval isn’t usually one of them. Traditional lenders require verifiable, consistent income—often two years’ worth. But self-employed Canadians typically write off significant expenses, reducing their declared income. Alternative lenders are more flexible and understanding of self-employed income structures. If your business is profitable and your personal finances are healthy, you may qualify even with lower stated income. Even if interest rates are slightly higher, this option is often worth it—especially when balanced against tax planning and business deductions . 3. You Earn Non-Traditional Income Today’s income sources aren’t always conventional. If you earn through: Airbnb rentals Tips and gratuities Rideshare or delivery apps (like Uber or Uber Eats) Commissions or contracts You might face challenges with traditional lenders. Alternative lenders are often more willing to work with these non-standard income streams , especially if the rest of your mortgage application is strong. Some will consider a shorter income history or evaluate your average earnings in a more flexible way. 4. You Need Expanded Debt-Service Ratios Canada’s mortgage stress test has made it harder for many borrowers to qualify with big banks. Alternative lenders can offer more generous debt-service ratio limits —meaning you might be able to qualify for a larger mortgage or a more suitable home, especially in competitive markets. While traditional GDS/TDS limits typically sit at 35/42 or 39/44 (depending on your credit), some alternative lenders will go higher, especially if: You have a larger down payment Your loan-to-value ratio is lower Your overall financial profile is strong It’s not a free-for-all—but it’s more flexible than bank lending. So, Is Alternative Lending Right for You? Alternative lending is designed to offer solutions when life doesn’t fit the traditional mold . Whether you're rebuilding credit, running your own business, or earning income in new ways, this path could help you get into a home sooner—or keep your current one. And here’s the key: You can only access alternative lenders through the mortgage broker channel . Let’s Explore Your Options Not sure where you fit? That’s okay. Every mortgage story is unique—and I’m here to help you write yours. If you’re curious about alternative mortgage products, want a second opinion, or need help getting approved, let’s talk . I’d be happy to help you explore the best solution for your situation. Reach out anytime. It would be a pleasure to work with you.
By Kevin Blue • October 7, 2026
Why Work With an Independent Mortgage Professional? If you’re in the market for a mortgage, here’s the most important thing to know: Working with an independent mortgage professional can save you money and provide better options than dealing directly with a single bank. If that’s all you read—great! But if you’d like to understand why that statement is true, keep reading. The Best Mortgage Isn’t Just About the Lowest Rate It’s easy to fall for slick marketing that promotes ultra-low mortgage rates. But the lowest rate doesn’t always mean the lowest cost . The best mortgage is the one that costs you the least amount of money over time —not just the one with the flashiest headline rate. Things like: Prepayment penalties Portability Flexibility to refinance Amortization structure Fixed vs. variable terms …can all affect the true cost of your mortgage. An independent mortgage professional looks beyond the rate. They’ll help you find a product that fits your unique financial situation , long-term goals, and lifestyle—so you’re not hit with expensive surprises down the road. Save Time (and Your Sanity) Applying for a mortgage can be complicated. Every lender has different rules, documents, and policies—and trying to navigate them all on your own can be time-consuming and frustrating. When you work with an independent mortgage professional: You fill out one application They shop that application across multiple lenders You get expert advice tailored to your needs This means less paperwork , less stress , and more confidence in your options. Get Unbiased Advice That Puts You First Bank specialists work for the bank. Their job is to sell you that bank’s mortgage products—whether or not it’s the best deal for you. Independent mortgage professionals work for you. They’re provincially licensed, and their job is to help you: Compare multiple lenders Understand the fine print Make informed, long-term financial decisions And the best part? Their services are typically free to you . Mortgage professionals are paid a standardized fee by the lender when a mortgage is placed—so you get expert guidance without any out-of-pocket cost. Access More Mortgage Options When you go to your bank, you’re limited to that bank’s mortgage products. When you go to an independent mortgage professional, you get access to: Major banks Credit unions Monoline lenders (who only offer mortgages) Alternative and private lenders (if needed) That’s far more choice , and a much better chance of finding a mortgage that truly fits your needs and goals. The Bottom Line If you want to: Save money over the life of your mortgage Save time by avoiding unnecessary back-and-forth Access more lenders and products Get honest, client-first advice …then working with an independent mortgage professional is one of the smartest decisions you can make. Let’s Make a Plan That Works for You If you're ready to talk about mortgage financing—or just want to explore your options—I'm here to help. Let's connect and put together a strategy that makes sense for your goals and your future. Reach out anytime. I’d be happy to help.
By Kevin Blue • September 30, 2026
Buying a Home? Follow These 6 Key Steps for a Smooth Experience Buying a home is likely one of the biggest financial decisions you’ll ever make. It’s exciting—but it can also be overwhelming, especially when it comes to understanding how mortgage financing works. To help make the process smoother (and far less stressful), here are six essential steps every homebuyer should follow: 1. Start With a Mortgage Professional—Not MLS It’s tempting to start your home search by scrolling through listings and booking showings—but the real first step should be speaking with an independent mortgage professional . Unlike a bank that offers only one set of products, an independent mortgage expert has access to multiple lenders and options . That means better advice, better rates, and a better chance of finding a mortgage that truly fits your needs. 2. Build a Personalized Mortgage Plan Unless you’re buying your home with cash, you’ll need a solid financing strategy. That means: Reviewing your credit score Running affordability calculations Exploring different mortgage types, terms, and features Understanding down payments and closing costs The sooner you start planning, the more confident you’ll feel. Don’t wait until you’ve found the “perfect” property— get ahead of the process now . 3. Figure Out What You Can Actually Afford What a lender says you can borrow doesn’t always match what you can comfortably pay each month. Take a close look at your budget, lifestyle, and spending habits. Think about how your mortgage payments, property taxes, utilities, and other costs will fit into your everyday cash flow. Avoid the stress of being house-poor by knowing your real-life affordability , not just your paper pre-approval. 4. Get Pre-Approved the Right Way A true mortgage pre-approval isn’t just entering numbers into an online calculator. It means: Completing a mortgage application Submitting all your required documentation Having a mortgage professional fully assess your file When you’re officially pre-approved, you’ll shop for homes with confidence , knowing what you qualify for and that you’re financially ready. 5. Submit Your Documents Promptly and Stay Flexible Once you find a property and your offer is accepted, time is of the essence. That’s when all the upfront work you’ve done really pays off. Be ready to: Provide additional documentation if requested Respond to your mortgage professional quickly Stay flexible and proactive throughout the approval process Your lender needs to verify everything before finalizing the loan, so staying organized is key. 6. Don’t Make Big Financial Changes Before Closing Once you’ve secured financing and waived your conditions, freeze your finances until after you get the keys. Seriously—don’t: Change jobs Apply for new credit Take out a loan Make a large withdrawal Even small changes can throw off your approval. Keep everything status quo until you officially take possession. Recap: 6 Steps to a Smooth Home Purchase Connect with an independent mortgage professional Create a mortgage plan early Know what you can afford (not just what you qualify for) Get fully pre-approved Stay on top of documentation Avoid major financial changes before possession Ready to Buy with Confidence? If you’re thinking about buying a home—or just want to know what’s possible—let’s talk. I’ll help you map out a personalized plan that makes your homebuying journey feel simple, strategic, and stress-free. Reach out anytime. I’d love to help you get started.
By Kevin Blue • September 23, 2026
Cashback Mortgages: Are They Worth It? Here’s What You Need to Know If you’ve been exploring mortgage options and come across the term cashback mortgage , you might be wondering what exactly it means—and whether it’s a smart move. Let’s break it down in simple terms. What Is a Cashback Mortgage? A cashback mortgage is just like a regular mortgage—but with one extra feature: you receive a lump sum of cash when the mortgage closes . This cash is typically: A fixed amount , or A percentage of the total mortgage , usually between 1% and 7% , depending on your mortgage term and lender. The money is tax-free and paid directly to you on closing day. What Can You Use the Cashback For? There are no restrictions on how you use the funds. Here are some common uses: Covering closing costs Buying new furniture Renovations or home upgrades Paying off high-interest debt Boosting your cashflow during a tight transition Whether it’s to help you settle in or catch up financially, cashback can offer a helpful buffer— but it comes at a cost . The True Cost of a Cashback Mortgage Here’s the part many people overlook: cashback mortgages come with higher interest rates than standard mortgages. Why? Because the lender is essentially advancing you a small loan upfront—and they’re going to make that money back (and then some) through your mortgage payments. So while the upfront cash feels like a bonus, you’ll pay more in interest over time to have that convenience. Breaking Down the Numbers It’s hard to give a blanket answer about how much more you’ll pay since it depends on: Your interest rate The cashback amount The mortgage term Your payment schedule This is why it’s important to run the numbers with a mortgage professional who can help you compare this option with others based on your personal financial situation. Are You Eligible for a Cashback Mortgage? Not everyone qualifies. Cashback mortgages generally come with stricter requirements . Lenders often want to see: Excellent credit history Strong, stable income Low debt-to-income ratio If your mortgage file includes anything “outside the box”—like being self-employed or recently changing jobs—qualifying for a cashback mortgage might be tough. What If You Need to Break the Mortgage? This is one of the biggest risks with cashback mortgages. If your circumstances change and you need to break your mortgage early, you could be on the hook for: Paying back some or all of the cashback you received, and A prepayment penalty (typically the interest rate differential or 3 months’ interest—whichever is higher) That can be a very expensive combination. So if there’s even a chance you might need to sell, refinance, or move before your term is up, a cashback mortgage might not be the best fit. Should You Consider a Cashback Mortgage? Maybe—but only with eyes wide open. Cashback mortgages can be helpful in the right scenario, but they’re not free money. They’re a lending tool that benefits the lender , and the key is knowing exactly what you’re agreeing to. Final Thoughts: Talk to an Expert First Choosing the right mortgage isn’t just about the lowest rate or the biggest perk—it’s about making a choice that fits your whole financial picture. If you’re considering a cashback mortgage, or just want to explore all your options, let’s talk. As an independent mortgage professional , I can help you weigh the pros and cons of various products, so you can make a confident, informed decision. Have questions? I’d be happy to help—reach out anytime.
By Kevin Blue • September 16, 2026
Thinking About Buying a Second Property? Here’s What to Know Buying a second property is an exciting milestone—but it’s also a big financial decision that deserves thoughtful planning. Whether you're dreaming of a vacation retreat, building a rental portfolio, or looking to support a family member with a place to live, there are plenty of reasons to consider a second home. But before you jump in, it's important to understand the strategy and steps involved. Start with “Why” The best place to begin? Clarify your motivation. Ask yourself: Why do I want to buy a second property? What role will it play in my life or finances? How does this fit into my long-term goals? Whether your focus is lifestyle, income, or legacy planning, knowing your “why” will help you make smarter decisions from the start. Talk to a Mortgage Expert Early Once you’ve nailed down your goals, the next step is to sit down with an independent mortgage professional. Why? Because buying a second property isn't quite the same as buying your first. Even if you’ve qualified before, financing a second home has unique considerations—especially when it comes to down payments, debt ratios, and how lenders assess risk. How Much Do You Need for a Down Payment? Here’s where the purpose of the property really matters: Owner-occupied or family use: You may qualify with as little as 5–10% down, depending on the property and lender. Income property: Expect to put down 20–35%, especially for short-term rentals or if it won’t be occupied by you or a family member. Your down payment amount can be one of the biggest hurdles—but with strategic planning, it’s often manageable. Ways to Fund the Down Payment If you don’t have the full amount in cash, you might be able to tap into your current home’s equity to help fund the purchase. Here are a few ways to do that: ✅ Refinance your existing mortgage to access additional funds ✅ Secure a second mortgage behind your current one ✅ Open a HELOC (Home Equity Line of Credit) ✅ Use a reverse mortgage (in certain age-qualified scenarios) ✅ Take out a new mortgage if your current home is mortgage-free These options depend on your income, credit, home value, and overall financial picture—another reason why having a pro in your corner matters. Second Property Strategy: It’s More Than Just Numbers This purchase should be part of a bigger financial plan—one that balances risk and reward. It’s about: Assessing your full financial health Maximizing your existing assets Minimizing your cost of borrowing Aligning your purchase with your long-term goals Ready to Take the Next Step? There’s no one-size-fits-all answer when it comes to buying a second property. That’s why it helps to talk things through with someone who understands both the big picture and the small details. If you’re ready to explore your options and build a plan to make that second property dream a reality, let’s connect. I’d love to help you take the next step with confidence.
By Kevin Blue • September 9, 2026
If you're a homeowner juggling multiple debts, you're not alone. Credit cards, car loans, lines of credit—it can feel like you’re paying out in every direction with no end in sight. But what if there was a smarter way to handle it? Good news: there is. And it starts with your home. Use the Equity You’ve Built to Lighten the Load Every mortgage payment you make, every bit your home appreciates—you're building equity. And that equity can be a powerful financial tool. Instead of letting high-interest debts drain your income, you can leverage your home’s equity to combine and simplify what you owe into one manageable, lower-interest payment. What Does That Look Like? This strategy is called debt consolidation , and there are a few ways to do it: Refinance your existing mortgage Access a Home Equity Line of Credit (HELOC) Take out a second mortgage Each option has its own pros and cons, and the right one depends on your situation. That’s where I come in—we’ll look at the numbers together and choose the best path forward. What Can You Consolidate? You can roll most types of consumer debt into your mortgage, including: Credit cards Personal loans Payday loans Car loans Unsecured lines of credit Student loans These types of debts often come with sky-high interest rates. When you consolidate them into a mortgage—secured by your home—you can typically access much lower rates, freeing up cash flow and reducing financial stress. Why This Works Debt consolidation through your mortgage offers: Lower interest rates (often significantly lower than credit cards or payday loans) One simple monthly payment Potential for faster repayment Improved cash flow And if your mortgage allows prepayment privileges—like lump-sum payments or increased monthly payments—those features can help you pay everything off even faster. Smart Strategy, Not Just a Quick Fix This isn’t just about lowering your monthly bills (although that’s a major perk). It’s about restructuring your finances in a way that’s sustainable, efficient, and empowering. Instead of feeling like you're constantly catching up, you can create a plan to move forward with confidence—and even start saving again. Here’s What the Process Looks Like: Review your current debts and cash flow Assess how much equity you’ve built in your home Explore consolidation options that fit your goals Create a personalized plan to streamline your payments and reduce overall costs Ready to Regain Control? If your debts are holding you back and you're ready to use the equity you've worked hard to build, let's talk. There’s no pressure—just a practical conversation about your options and how to move toward a more flexible, debt-free future. Reach out today. I’m here to help you make the most of what you already have.
By Kevin Blue • August 26, 2026
So, you’re thinking about buying a home. You’ve got Pinterest boards full of kitchen inspo, you’re casually scrolling listings at midnight, and your friends are talking about interest rates like they’re the weather. But before you dive headfirst into house hunting— wait . Let’s talk about what “ready” really means when it comes to one of the biggest purchases of your life. Because being ready to own a home is about way more than just having a down payment (although that’s part of it). Here are the real signs you're ready—or not quite yet—to take the plunge into homeownership: 1. You're Financially Stable (and Not Just on Payday) Homeownership isn’t a one-time cost. Sure, there’s the down payment, but don’t forget about: Closing costs Property taxes Maintenance & repairs Insurance Monthly mortgage payments If your budget is stretched thin every month or you don’t have an emergency fund, pressing pause might be smart. Owning a home can be more expensive than renting in the short term—and those unexpected costs will show up. 2. You’ve Got a Steady Income and Job Security Lenders like to see consistency. That doesn’t mean you need to be at the same job forever—but a reliable, documented income (ideally for at least 2 years) goes a long way in qualifying for a mortgage. Thinking of switching jobs or going self-employed? That might affect your eligibility, so timing is everything. 3. You Know Your Credit Score—and You’ve Worked On It Your credit score tells lenders how risky (or trustworthy) you are. A higher score opens more doors (literally), while a lower score may mean higher rates—or a declined application. Pro tip: Pull your credit report before applying. Fix errors, pay down balances, and avoid taking on new debt if you’re planning to buy soon. 4. You’re Ready to Stay Put (At Least for a Bit) Buying a home isn’t just a financial decision—it’s a lifestyle one. If you’re still figuring out your long-term plans, buying might not make sense just yet. Generally, staying in your home for at least 3–5 years helps balance the upfront costs and gives your investment time to grow. If you’re more of a “see where life takes me” person right now, that’s totally fine—renting can offer the flexibility you need. 5. You’re Not Just Buying Because Everyone Else Is This one’s big. You’re not behind. You’re not failing. And buying a home just because it seems like the “adult” thing to do is a fast way to end up with buyer’s remorse. Are you buying because it fits your goals? Because you’re ready to settle, invest in your future, and take care of a space that’s all yours? If the answer is yes—you’re in the right headspace. So… Are You Ready? If you’re nodding along to most of these, amazing! You might be more ready than you think. If you’re realizing there are a few things to get in order, that’s okay too. It’s way better to prepare well than to rush into something you're not ready for. Wherever you’re at, I’d love to help you take the next step—whether that’s getting pre-approved, making a plan, or just asking questions without pressure. Let’s make sure your homebuying journey starts strong. Connect anytime—I’m here when you’re ready.
Show More